Under $1,000 tier
What car insurance costs in Idaho
Idaho's below-average premium broken down by coverage, the limits Idaho law sets, and how to keep a low bill from creeping up.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $864
- Change from 2022
- +12%
- Minimum liability limits
- 25/50/15
- Uninsured drivers, 2023
- 6.4%
Bottom line
Idaho is one of the less expensive states to insure a car: drivers spent an average of $864 per insured car in 2023, 33% below the U.S. average of $1,282, and full coverage averaged $981. All three coverage lines cost less than the national averages. Idaho requires 25/50/15 liability, includes uninsured and underinsured motorist coverage unless you reject it in writing, and forbids insurers from raising a premium based primarily on credit.
The Idaho bill, line by line
Guardbrook
Average car insurance bill, 2023
Idaho
Liability$482
Collision$324
Comprehensive$175
Full coverage$981
Average spend per car$864
Compared with the U.S.−33%
Uninsured drivers6.4%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
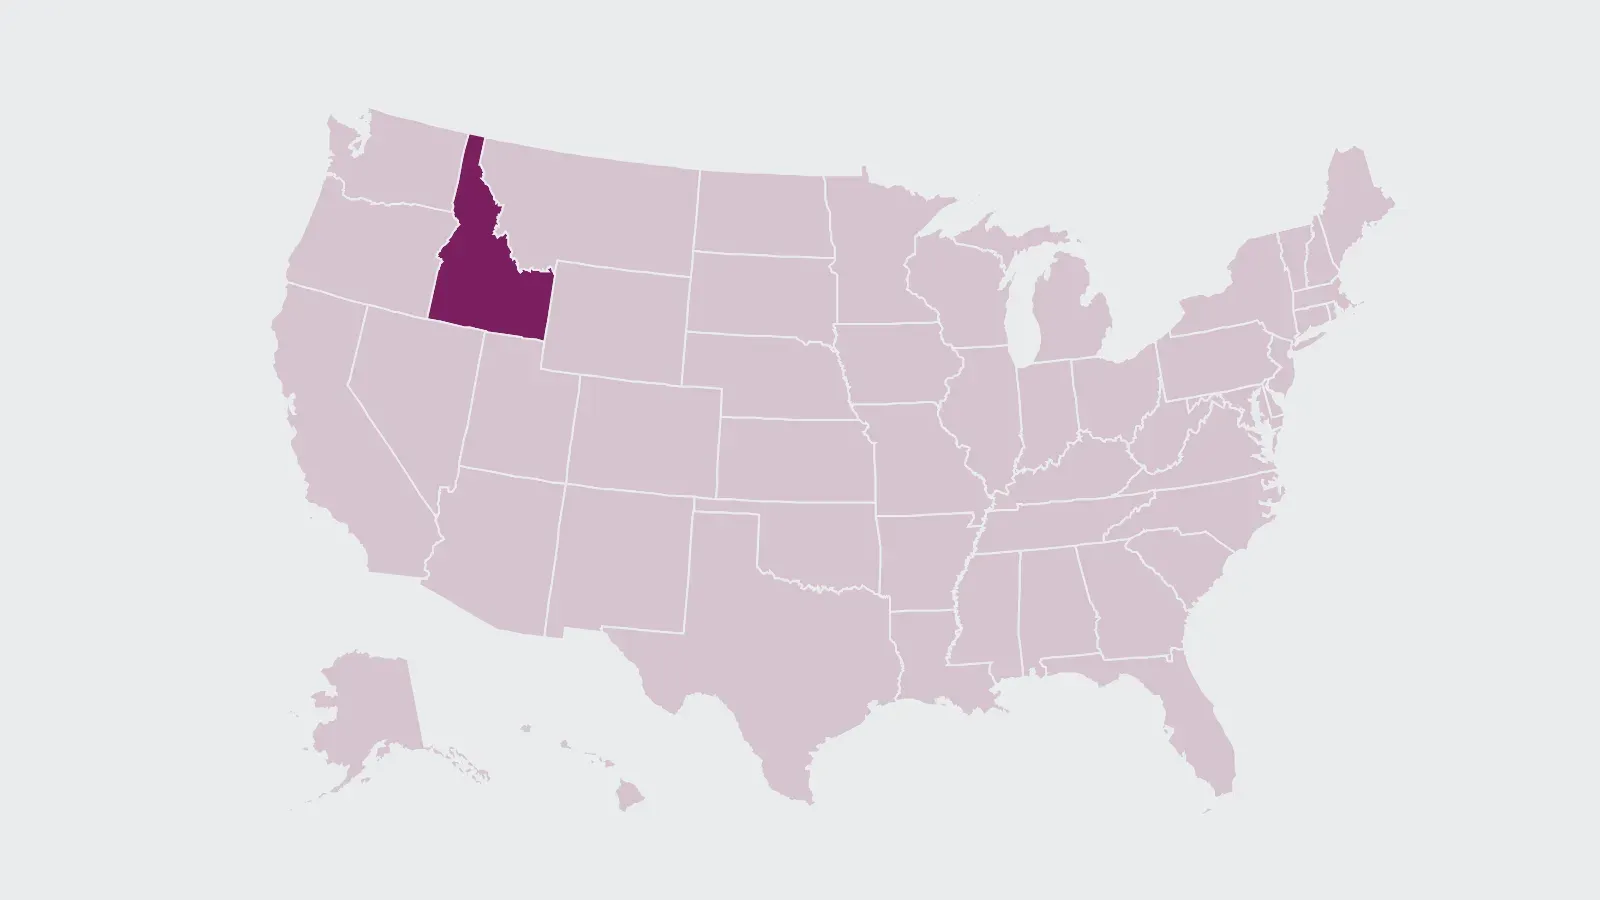
Price tier on the map
Under $1,000 a year
- Minimum liability limits
- 25/50/15
- UM and UIM bodily injury coverage included unless rejected in writing
- Credit-based insurance scores
- Allowed, not as the primary basis
- Idaho Code § 41-1843: credit can't outweigh all other factors in a higher premium or a refusal
- Regulator
- Idaho Department of Insurance
Idaho's premium, coverage by coverage
The National Association of Insurance Commissioners (NAIC) compiles the premiums insurers collect in every state. In its 2023 figures, the newest it has published by state, Idaho's average expenditure was $864 per insured car, 12% above the $772 of 2022. That average covers liability-only cars as well as fully insured ones. A car with liability, collision and comprehensive together averaged $981.
| Coverage | Idaho | United States |
|---|---|---|
| Liability | $482 | $737 |
| Collision | $324 | $464 |
| Comprehensive | $175 | $238 |
| All three (combined premium) | $981 | $1,438 |
| Average expenditure | $864 | $1,282 |
Each line is well under the U.S. number: liability by about 35%, collision by about 30% and comprehensive by about 26%. Only North Dakota and Maine had a lower average expenditure in 2023. Low averages still rose 12% in a year, though, roughly in step with the national increase, so a cheap state isn't immune to rising bills. The NAIC doesn't give reasons for the levels. What moves your own price is personal; how far you drive is one factor, covered in annual mileage and price.
Idaho's required coverage
The Idaho Department of Insurance says each personal-use vehicle registered in Idaho needs bodily injury liability of at least $25,000 per person and $50,000 per accident, and property damage liability of at least $15,000. In shorthand, 25/50/15.
- Uninsured (UM) and underinsured (UIM) motorist bodily injury coverage comes with the policy unless a named insured rejects it in writing.
- The Idaho UM/UIM Disclosure Form must be given to you. It explains both coverages and lets you reject either one or both.
- Collision, comprehensive and medical payments appear on the Department's list of optional coverages.
The Insurance Research Council estimates that only 6.4% of Idaho drivers were uninsured in 2023, among the lowest shares in the country. That can make rejecting UM coverage look tempting, but underinsured drivers, those carrying only the 25/50 minimum, are a separate risk. Our guide to coverage limits and deductibles helps you weigh it.
Idaho's limits on rates and credit
The Department of Insurance's rates section reviews rate filings for private passenger auto insurance. Its stated goal is to make sure rates are not inadequate, excessive or unfairly discriminatory. Within that standard, each insurer prices on its own, which is why quotes vary.
Idaho Code § 41-1843 sets its own test for credit. An insurer may not charge a higher premium, or cancel, nonrenew or refuse a personal policy, based primarily on your credit rating or history. The law defines "primarily" precisely: credit can't carry more weight in the decision than all the other criteria combined. So credit can still count, but it can't dominate. Read more about credit-based insurance scores.
When a driver can't find coverage
Idaho Code § 41-1441 lets casualty insurers share out drivers who are entitled to insurance but can't get it the ordinary way, with plan premiums held to the same not-excessive standard. In practice this is the Idaho Automobile Insurance Plan. Its processing center, the Western Association of Automobile Insurance Plans, connects each applicant with an insurer; an agent submits the application. Our page on assigned risk plans explains what to expect.
Keeping an Idaho premium low
- Re-shop at renewal. Ask two or three insurers to quote the same limits and deductibles; differences between companies can matter more than any single discount.
- Try a usage-based program if you drive carefully. Some insurers price on how you actually drive; our guide to telematics insurance covers what is tracked and whether a price can rise.
- Match the deductible to your savings. Collision is already well below the U.S. average in Idaho, so check whether a higher deductible still saves enough to be worth the extra risk.
- Use the Department's consumer lines. The Consumer Hotline is 1-800-721-3272 and Consumer Affairs is (208) 334-4250; complaints can also be filed online.
Questions drivers ask
Is car insurance cheap in Idaho?
Compared with most states, yes. NAIC data for 2023 put Idaho's average expenditure at $864 per insured car, 33% below the U.S. average, with full coverage at $981.
What are Idaho's minimum car insurance limits?
25/50/15: $25,000 per person and $50,000 per accident for bodily injury, and $15,000 for property damage.
Can I reject uninsured motorist coverage in Idaho?
Yes. UM and UIM coverage is included unless a named insured rejects it in writing, using the Idaho UM/UIM Disclosure Form your insurer provides.
Can my credit raise my Idaho car insurance premium?
Not when credit is the primary basis. Idaho Code § 41-1843 bars a higher premium when credit outweighs all other factors combined.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Idaho Department of Insurance — Required auto coverage
- Idaho Department of Insurance — Auto insurance (consumer contacts)
- Idaho Department of Insurance — Rates and forms
- Idaho Code § 41-1843 — Credit rating or history
- Idaho Code § 41-1441 — Assigned risks
- AIPSO — Idaho Automobile Insurance Plan
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Annual mileage
One of three rating factors named in California law, and a common discount elsewhere. How miles are checked.
-
Way to save
Telematics and usage-based insurance
What tracking apps and plug-ins record, whether your price can rise, and 5 privacy questions to ask first.
-
Shopping guide
Switching insurers without a gap
Start the new policy first, cancel in writing, tell the lender. A North Carolina lapse can cost up to $200 in fees.