$1,500 or more tier
What car insurance costs in Louisiana
How far Louisiana's average bill runs above the national one line by line, what state law requires, and the options that can bring a premium down.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $1,749
- Change from 2022
- +12%
- Minimum liability limits
- 15/30/25
- Uninsured drivers, 2023
- 11.7%
Bottom line
Louisiana drivers spent an average of $1,749 per insured car in 2023, about 36% more than the U.S. average of $1,282, and a fully covered car averaged $1,979. Every coverage line is above the national figure. The legal minimum is only 15/30/25, uninsured motorist coverage comes with the policy unless you reject it on the state's form, and an uninsured driver gives up the first $15,000 of injury and $25,000 of property damage claims. Comparing insurers and claiming the discounts you qualify for are the main levers.
The Louisiana bill, line by line
Guardbrook
Average car insurance bill, 2023
Louisiana
Liability$1,052
Collision$581
Comprehensive$346
Full coverage$1,979
Average spend per car$1,749
Compared with the U.S.+36%
Uninsured drivers11.7%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
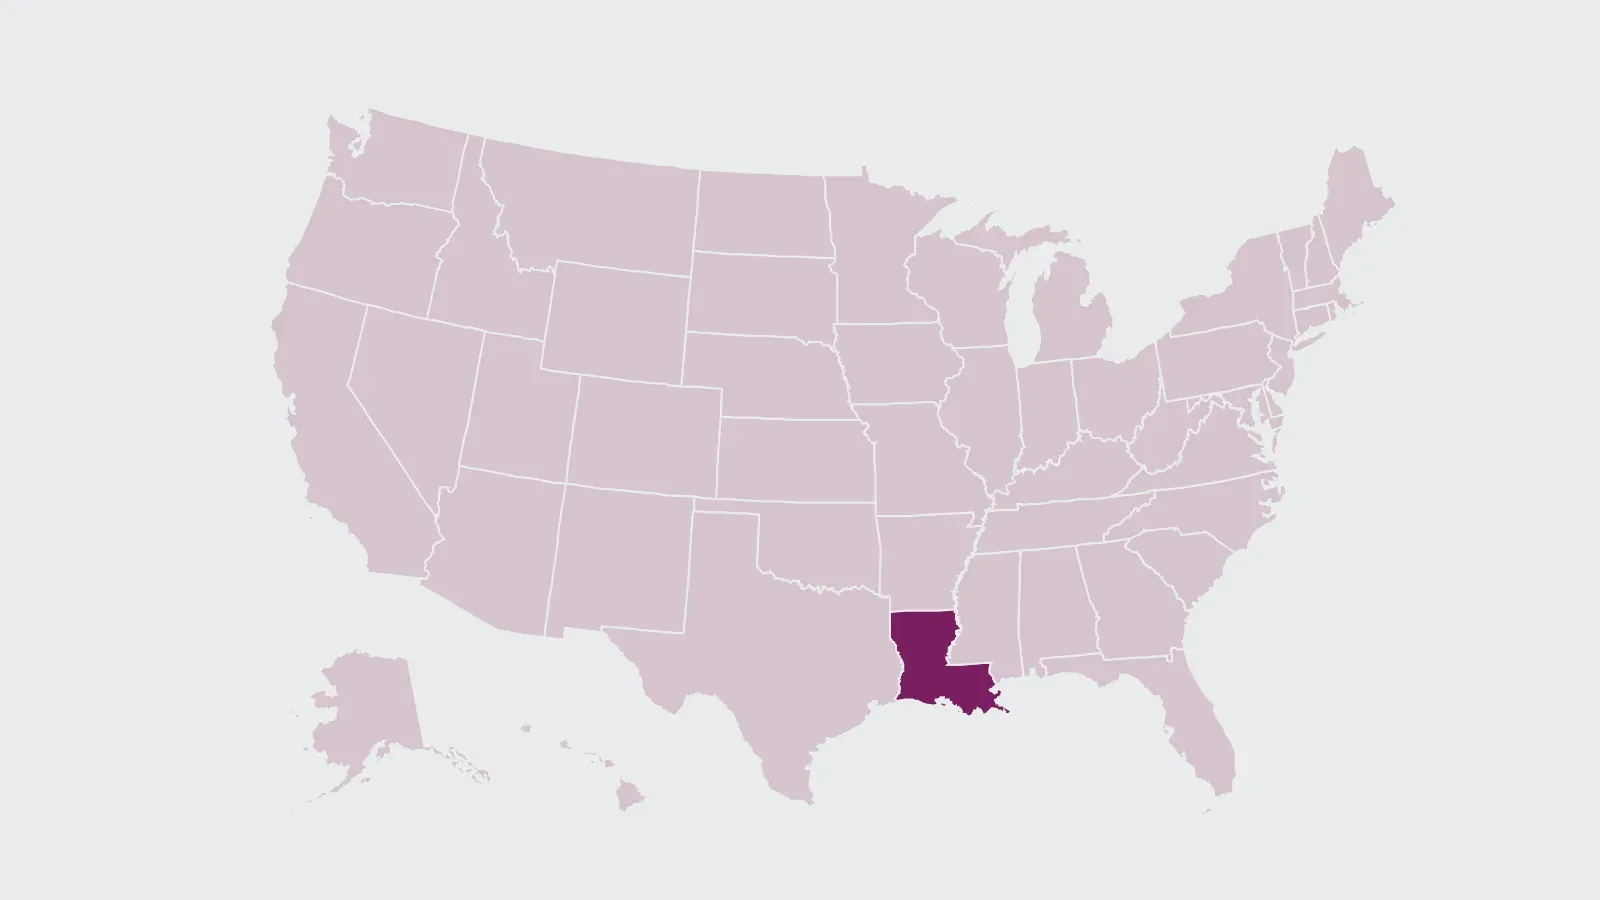
Price tier on the map
$1,500 or more a year
- Minimum liability limits
- 15/30/25
- UM included at liability limits unless rejected on the commissioner's form; no pay, no play for uninsured drivers
- Credit-based insurance scores
- Allowed, not as the only factor
- R.S. 22:1504: not the sole basis to deny, cancel, nonrenew or set a renewal rate; LDI consumer guide
- Regulator
- Louisiana Department of Insurance
Louisiana's premium, coverage by coverage
The National Association of Insurance Commissioners (NAIC) totals the premiums insurers charge in each state. In 2023, its latest state-level year, the average Louisiana expenditure came to $1,749 per insured car, 12% above the $1,558 of 2022. Expenditure includes cars carrying liability only; the combined premium for a car with liability, collision and comprehensive was $1,979.
| Coverage | Louisiana | United States |
|---|---|---|
| Liability | $1,052 | $737 |
| Collision | $581 | $464 |
| Comprehensive | $346 | $238 |
| All three (combined premium) | $1,979 | $1,438 |
| Average expenditure | $1,749 | $1,282 |
The gap shows up everywhere. Liability, the coverage every Louisiana owner must buy, averages $1,052, about 43% above the U.S. figure. Comprehensive is about 45% higher and collision about 25% higher. The NAIC tables don't explain the difference, so we won't guess at it here; what they do show is that a Louisiana driver has more money at stake when picking an insurer. Your own price also depends on where you park; see how location sets a price.
Louisiana's legal minimum, and the no pay, no play rule
Louisiana requires liability coverage on every car you own, at limits of at least $15,000 for one injured person, $30,000 for all injuries in one accident and $25,000 for property damage (La. R.S. 32:900). The per-person injury limit is lower than in most states, and a serious injury can use it up quickly.
- Uninsured motorist coverage is included automatically, at the same limits as your bodily injury liability, unless the named insured rejects it, picks lower limits or chooses economic-only coverage on a form prescribed by the insurance commissioner (La. R.S. 22:1295).
- Economic-only UM costs less because it pays for actual injury costs but not pain and suffering.
- No pay, no play: a driver without insurance can't collect the first $15,000 of injury damages or the first $25,000 of property damage, whoever caused the crash, according to the Louisiana Department of Insurance (LDI).
- Collision and comprehensive are not part of the legal minimum, but lenders may require them on a financed car.
The Insurance Research Council estimates that 11.7% of Louisiana drivers were uninsured in 2023, below the 15.4% national rate. Before trimming uninsured motorist limits to save money, see how limits and deductibles change what you are protected against.
How Louisiana regulates car insurance prices
The LDI's rate and rule filing handbook (June 2025 edition) describes Louisiana as a file-and-use state: insurers file their rates with the department, and a filing is deemed approved unless the commissioner objects within the period the law sets. Each company still builds its own rates.
The LDI's consumer guide says race and religion may not be used to set rates, while credit information, gender and marital status may affect a premium, along with age, location, vehicle, coverage, deductibles, driving record and mileage. R.S. 22:1504 sets limits: an insurer can't deny, cancel or nonrenew a policy, or set your renewal rate, solely on credit information, and you can ask to be re-underwritten on current credit at your annual renewal. For how credit enters the price, read our page on credit-based insurance scores.
If insurers won't write your policy
The LDI calls the Louisiana Automobile Insurance Plan the insurer of last resort for Louisiana drivers. It serves eligible drivers who can't find coverage in the voluntary market, and only agents with a Louisiana auto insurance license can write business through it, so ask your agent. Our guide to assigned-risk plans explains how to move back to the regular market later.
Ways to lower a Louisiana premium
- Apply for the military discount if you serve. Active-duty members, reservists and Louisiana National Guard members stationed or based in Louisiana can get 25% off the liability portion of the premium. Send the state application form and proof of service to your insurer.
- Compare several insurers. With averages this high, the spread between companies matters. Request quotes on matching coverage and compare them line by line.
- Ask about voluntary discounts. The LDI lists multi-car, bundling, telematics, good-student, senior, defensive driving, teen driver education and safety-device discounts that insurers may offer; eligibility and amounts vary.
- Check complaint records and complain if needed. The LDI's online complaint index compares companies' complaint histories, and its consumer line is 800-259-5300. Complaints can be filed online.
Questions drivers ask
How much more does car insurance cost in Louisiana than nationally?
About 36% more on average. The NAIC put Louisiana's 2023 expenditure at $1,749 per insured car against $1,282 nationally, and full coverage at $1,979 against $1,438.
What is Louisiana's minimum car insurance?
15/30/25: $15,000 for one person's injuries, $30,000 for all injuries in one accident and $25,000 for property damage, under La. R.S. 32:900.
What happens if I drive uninsured in Louisiana and someone hits me?
Under the no pay, no play rule you can't recover the first $15,000 of injury damages or the first $25,000 of property damage, even if the other driver was at fault. A gap in coverage also tends to raise later quotes; see insurance lapses.
Can I reject uninsured motorist coverage in Louisiana?
Yes, but only on the form prescribed by the insurance commissioner, signed by the named insured. The same form lets you choose lower limits or cheaper economic-only coverage.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Louisiana State Legislature — R.S. 22:1504, use of credit information
- Louisiana Department of Insurance — Auto insurance
- Louisiana Department of Insurance — Consumer's Guide to Auto Insurance (rev. 03/2026)
- Louisiana Department of Insurance — Military discount for auto insurance premiums
- Louisiana Department of Insurance — Rate and rule filing handbook (June 2025)
- La. R.S. 32:900 — Motor vehicle liability policy (Justia)
- La. R.S. 22:1295 — Uninsured motorist coverage (Justia)
- AIPSO — Louisiana Automobile Insurance Plan
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Insurance lapse
A gap can cost you twice: state penalties (a $600 fee in Virginia) and a higher price at the next quote.
-
Shopping guide
When to shop for car insurance
Renewal notices (45 days ahead in Maryland), moves, new cars and drivers, and old tickets that stop counting.
-
Way to save
Safe driver discounts
California's Good Driver rates must be at least 20% lower. What qualifies and what can cost you the discount.