$1,000–$1,249 tier
What car insurance costs in Tennessee
Tennessee's average bill set against the national one, the coverage the state requires, and the levers a driver can pull to lower it.
By Guardbrook Editorial Team Updated 6 min read
At a glance
- Average yearly spend, 2023
- $1,050
- Change from 2022
- +14%
- Minimum liability limits
- 25/50/25
- Uninsured drivers, 2023
- 21.3%
Bottom line
Tennessee drivers spent an average of $1,050 per insured car in 2023, about 18% less than the U.S. average of $1,282. A car carrying liability, collision and comprehensive averaged $1,212. The state's minimum is 25/50/25, and uninsured motorist coverage comes with every policy unless you reject it in writing. With roughly one Tennessee driver in five uninsured in 2023, that choice deserves a careful look before you trim it.
The Tennessee bill, line by line
Guardbrook
Average car insurance bill, 2023
Tennessee
Liability$542
Collision$441
Comprehensive$229
Full coverage$1,212
Average spend per car$1,050
Compared with the U.S.−18%
Uninsured drivers21.3%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
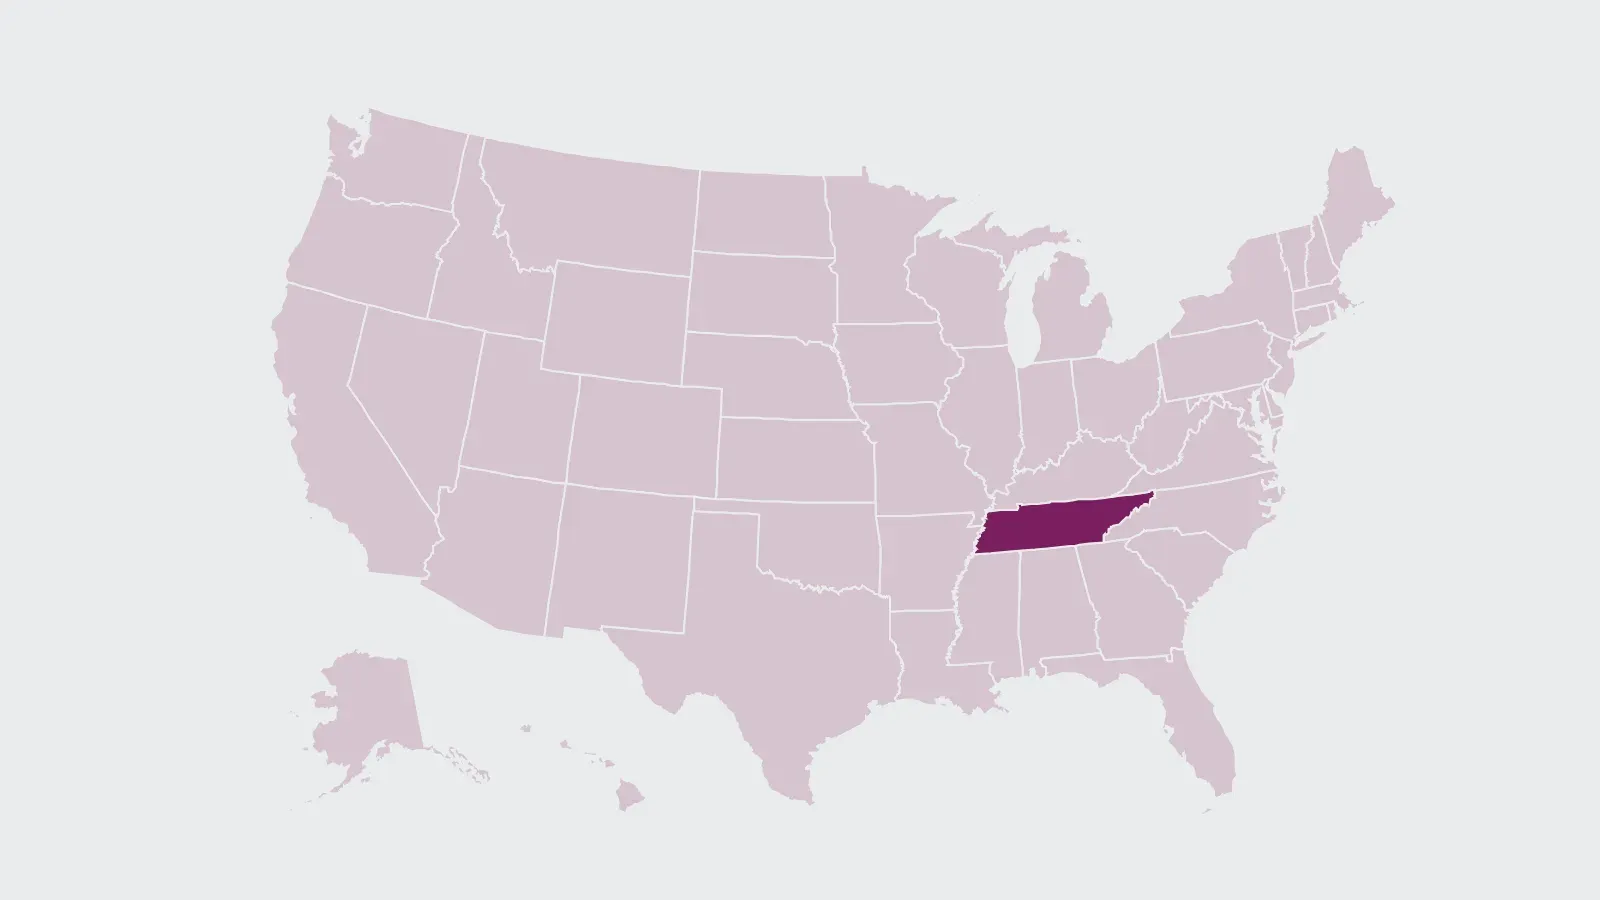
Price tier on the map
$1,000 to $1,249 a year
- Minimum liability limits
- 25/50/25
- Or a $65,000 single limit; uninsured motorist coverage included unless rejected in writing
- Credit-based insurance scores
- Allowed, not as the only factor
- Tenn. Code § 56-5-402: not the sole basis to deny, cancel, nonrenew or set renewal rates
- Regulator
- Tennessee Department of Commerce and Insurance
Tennessee's average bill, line by line
The National Association of Insurance Commissioners (NAIC) publishes what insurers actually collected in each state. In its latest state tables, for 2023, the average Tennessee expenditure was $1,050 per insured car, up 14% from $924 in 2022. That average blends cars with liability only and cars with full coverage. A car carrying all three main coverages had a combined average premium of $1,212.
| Coverage | Tennessee | United States |
|---|---|---|
| Liability | $542 | $737 |
| Collision | $441 | $464 |
| Comprehensive | $229 | $238 |
| All three (combined premium) | $1,212 | $1,438 |
| Average expenditure | $1,050 | $1,282 |
Every Tennessee line sits below the national figure, but not by the same amount. Liability, at $542, is about 26% under the U.S. average. Collision ($441) and comprehensive ($229) are only a few percent lower. So the gap with the rest of the country is mostly about the cost of covering damage you cause to others, not the cost of repairing your own car. Where you garage the car still moves your own price a lot; see how ZIP code affects a premium.
Coverage Tennessee requires
Tennessee's financial responsibility law sets the floor at $25,000 for injury to one person, $50,000 for injuries to two or more people and $25,000 for property damage in one accident, or a single limit of $65,000. The Department of Commerce and Insurance states the minimum as 25/50/25.
- Uninsured motorist coverage must be part of every policy, at limits equal to your bodily injury liability limits. Any named insured can reject it in writing or choose lower limits, though not below the state minimums.
- About 21.3% of Tennessee drivers were uninsured in 2023, by the Insurance Research Council's estimate, against 15.4% nationally. That makes the coverage you get to decline more likely to be needed here than in most states.
- Collision and comprehensive are not required by the state. A lender or leasing company will usually insist on them for a financed car.
Signing away uninsured motorist coverage lowers the premium, and the rejection binds everyone on the policy. Before you sign, compare what you save with what an injury could cost you; our page on limits and deductibles shows how to weigh that trade.
How Tennessee rules shape a premium
Tennessee's Department of Commerce and Insurance posts a document on personal auto policy rate changes on its Auto Insurance 101 page. It is worth opening before a renewal, so a higher bill doesn't come as a surprise.
Credit can count, within limits set by Tennessee Code § 56-5-402. An insurer may not deny, cancel or refuse to renew a personal policy, or set your renewal rate, solely on the basis of credit information; other factors independent of credit must be considered. An insurance score may not use income, gender, address, ethnic group, religion, marital status, nationality, education or occupation, and a company can't penalize you only because you have no credit history. Read more about credit-based insurance scores.
When regular insurers say no
A driver who can't find a policy in the normal market can be placed through Tennessee's residual-market plan, one of the state automobile insurance plans run through AIPSO. An agent can submit the application. Coverage there usually costs more, so it works best as a bridge while tickets and accidents age off your record. Our guide to assigned risk plans explains how they work.
Ways to lower a Tennessee bill
- Price the same policy at several insurers. Keep limits and deductibles identical so the quotes are comparable, and look at the department's rate-change document before renewal.
- Keep uninsured motorist coverage in view. If you need to cut cost, look at deductibles and optional extras first, since one driver in five here may have no insurance to pay you.
- Test a higher deductible. Raising the collision and comprehensive deductible lowers the premium; the deductible break-even calculator shows how long it takes to pay off.
- Ask for help if something looks wrong. Raise the problem with the company or agent first. If that fails, file a complaint online with Consumer Insurance Services; an insurance specialist answers general questions at 615-741-2218 or 1-800-342-4029 from outside Davidson County.
Questions drivers ask
Is car insurance cheaper in Tennessee than the national average?
On average, yes. NAIC data for 2023 put Tennessee's average expenditure at $1,050 per insured car against $1,282 nationally, and the full-coverage combined premium at $1,212 against $1,438.
What is the minimum car insurance in Tennessee?
Liability of $25,000 per injured person, $50,000 per accident for injuries and $25,000 for property damage (25/50/25), or a $65,000 single limit. Uninsured motorist coverage is included unless you reject it in writing.
Can I drop uninsured motorist coverage in Tennessee?
Yes. Any named insured can reject it in writing or pick lower limits, down to the state minimums. With an estimated 21.3% of Tennessee drivers uninsured in 2023, weigh the saving against the risk.
Can a Tennessee insurer use my credit to set my price?
It can consider credit, but not as the sole basis for denying, canceling or nonrenewing a policy or for setting renewal rates. See credit-based insurance scores.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Tennessee Department of Commerce and Insurance — Auto Insurance 101
- Tennessee Department of Commerce and Insurance — Insurance complaint instructions
- Tennessee Code § 55-12-102 — Proof of financial responsibility (Justia)
- Tennessee Code § 56-7-1201 — Uninsured motorist coverage (Justia)
- Tennessee Code § 56-5-402 — Restrictions on use of credit scores (Justia)
- AIPSO — State automobile insurance plan sites
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Coverage limits and deductibles
What 25/50/25 means, why liability is about half of a $1,438 full-coverage bill, and how to size a deductible.
-
Shopping guide
Complaining about a rate increase
Ask the insurer, use your adverse action rights, read the filing, then complain; Maryland gives you 30 days.
-
Way to save
Bundling home and auto
Wisconsin's regulator puts the package discount at up to 15%. Why a bundle can still cost more than two policies.