$1,000–$1,249 tier
What Alaskans pay for car insurance
The average Alaska premium against the national one, the coverage the state requires, how rates and credit are handled, and where you can trim the bill.
By Guardbrook Editorial Team Updated 5 min read
At a glance
- Average yearly spend, 2023
- $1,113
- Change from 2022
- +10%
- Minimum liability limits
- 50/100/25
- Uninsured drivers, 2023
- 12.5%
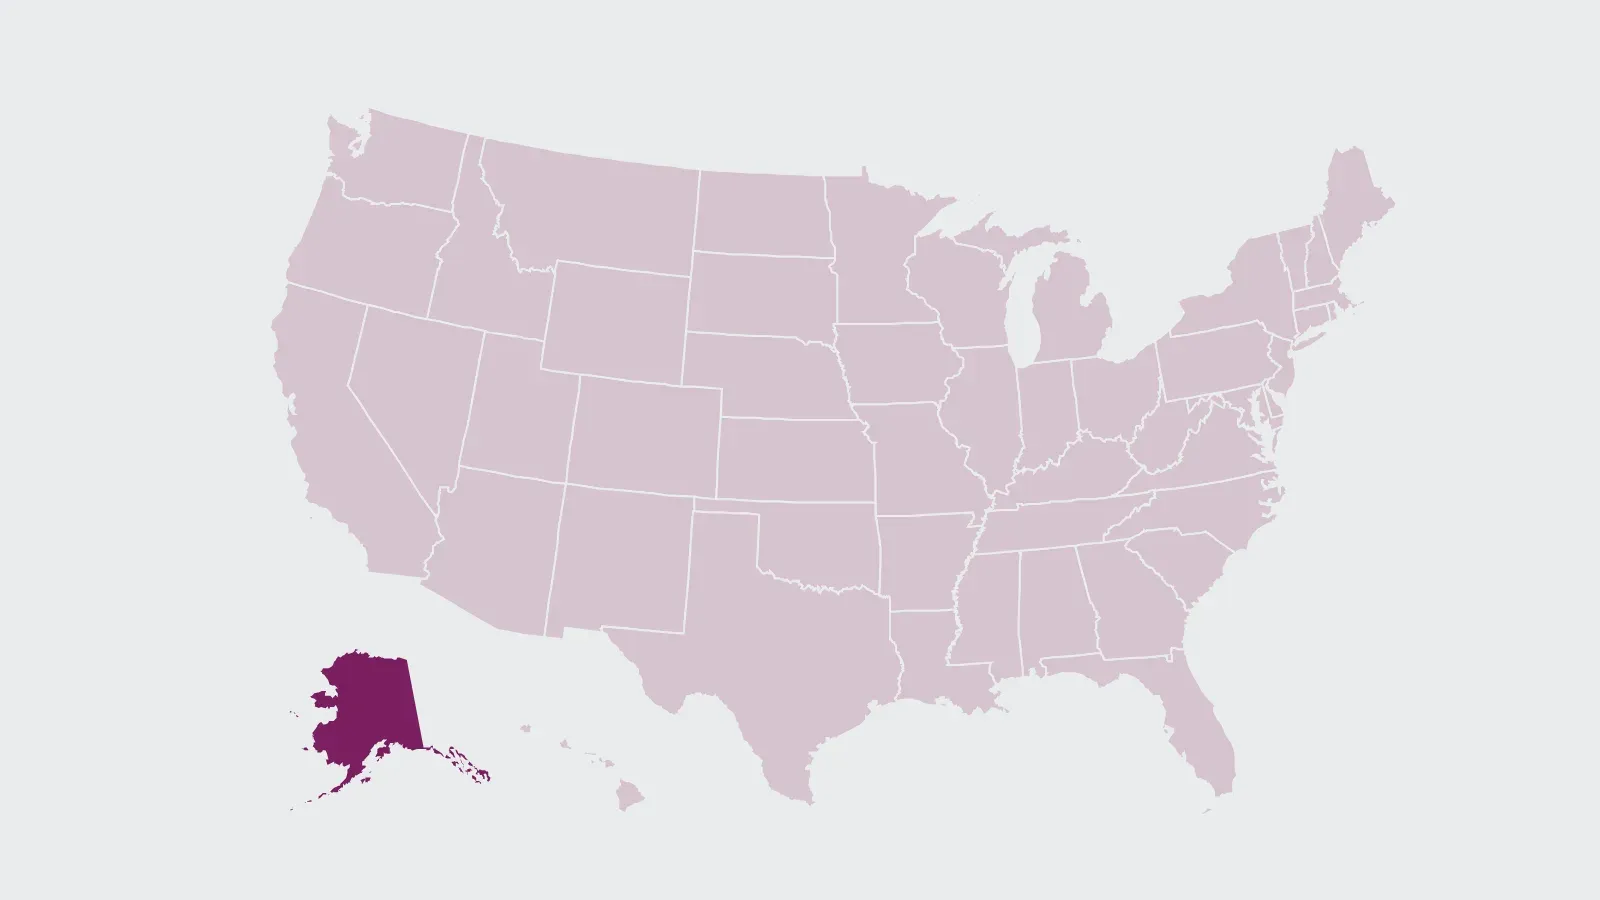
Bottom line
Alaska drivers spent an average of $1,113 per insured car in 2023, about 13% under the U.S. average of $1,282; a car with liability, collision and comprehensive averaged $1,262. Alaska's required liability limits, 50/100/25, are higher than in most states, and some remote communities are exempt from the mandate. Drivers 55 and older who finish an approved accident prevention course are entitled to a discount.
The Alaska bill, line by line
Guardbrook
Average car insurance bill, 2023
Alaska
Liability$624
Collision$458
Comprehensive$180
Full coverage$1,262
Average spend per car$1,113
Compared with the U.S.−13%
Uninsured drivers12.5%
Average yearly premiums per insured car (NAIC); uninsured share: Insurance Research Council estimate. Averages, not a quote. Where these numbers come from
Price tier on the map
$1,000 to $1,249 a year
- Minimum liability limits
- 50/100/25
- Not required in communities where registration isn't mandatory (AS 28.22.011)
- Credit-based insurance scores
- Allowed, with limits
- AS 21.36.460; exceptions for extraordinary life circumstances (Division of Insurance guide)
- Regulator
- Alaska Division of Insurance
Alaska's bill compared with the nation's
Each year the National Association of Insurance Commissioners (NAIC) publishes what insurers took in per insured car in every state. For 2023, the latest year available by state, the Alaska average expenditure was $1,113, up 10% from $1,014 in 2022. That figure includes liability-only cars. A car insured for liability, collision and comprehensive together cost $1,262 on average.
| Coverage | Alaska | United States |
|---|---|---|
| Liability | $624 | $737 |
| Collision | $458 | $464 |
| Comprehensive | $180 | $238 |
| All three (combined premium) | $1,262 | $1,438 |
| Average expenditure | $1,113 | $1,282 |
Two lines pull Alaska below the national average. Liability came to $624, about 15% under the U.S. figure, even though Alaska's legal minimum is double the 25/50 bodily injury limits many states set. Comprehensive, at $180, was about 24% lower. Collision was close to the U.S. average. Where you live and drive still matters a great deal; see how location shapes a premium.
The coverage Alaska law requires
The Alaska Division of Motor Vehicles lists the minimum under Alaska Statute 28.22.101: $50,000 per person and $100,000 per accident for bodily injury or death, and $25,000 for property damage, written 50/100/25. In areas where vehicle registration is not mandatory, insurance isn't required either; the DMV publishes the list of exempt communities. A driver with a ticket totaling 6 points or more in the past five years must carry liability insurance even there.
- Uninsured and underinsured motorist coverage must be offered. The Division of Insurance guide explains that if your choice isn't confirmed by your signature, the policy is issued with these limits matching your liability limits. The Insurance Research Council estimated 12.5% of Alaska drivers were uninsured in 2023.
- Medical payments is optional. It pays medical and funeral costs for people in your car without a finding of fault.
- Collision and comprehensive are optional under state law; a lender can still require them.
Lowering or rejecting uninsured motorist limits reduces the premium, but it also caps what you can collect from a driver with no insurance. Our page on limits and deductibles explains the trade-off.
Rates, credit and the state's role
Insurers file their personal auto rates and rating rules with the Alaska Division of Insurance. The division's filing checklist says the effective date must be at least 30 days after the division receives the filing. The division doesn't set prices: its consumer guide notes that rates vary among companies, which is why quotes for the same driver can differ.
Alaska law allows insurers to consider credit information when they choose applicants and set rates, with requirements and restrictions under AS 21.36.460. According to the division's guide, you can dispute the credit information used and ask for an exception if extraordinary life circumstances damaged your credit. See how credit-based insurance scores work.
Options for hard-to-place drivers
If regular insurers won't write you, the Alaska Automobile Insurance Plan assigns applicants to private insurance companies doing business in the state. Ask an agent to apply, or call the plan office run by AIPSO at (800) 227-4659. Expect to pay more than in the voluntary market; our guide to assigned-risk plans covers how to work your way back out.
How to pay less in Alaska
- Collect several quotes on identical coverage. Rates vary among companies, so the same limits and deductibles can carry very different prices.
- Claim the senior course discount if you qualify. State law requires insurers to give a discount to drivers over 55 who voluntarily complete an approved motor vehicle accident prevention course. More in our guide to the defensive driving course discount.
- Weigh a higher deductible. Use the deductible break-even calculator to see how many claim-free years it takes to come out ahead.
- Call for help. The Division of Insurance's consumer services staff can be reached at (907) 269-7900, or (800) 467-8725 toll-free in Alaska outside Anchorage.
Questions drivers ask
How does Alaska car insurance compare with the U.S. average?
NAIC's 2023 figures put the average Alaska expenditure at $1,113 per insured car, against $1,282 nationally. A full-coverage policy averaged $1,262 against $1,438.
What is the minimum car insurance in Alaska?
50/100/25 under Alaska Statute 28.22.101: $50,000 per person and $100,000 per accident for injuries, plus $25,000 for property damage. Some communities where registration isn't mandatory are exempt.
Is there a senior discount on car insurance in Alaska?
Yes. Insurers must give a discount to drivers over 55 who voluntarily complete an approved accident prevention course. Each company sets the amount.
Can Alaska insurers use my credit?
Yes, with restrictions. You can dispute the credit information used and ask for an exception for extraordinary life circumstances.
Where the figures come from
- NAIC — Auto Insurance Database Report 2022/2023 (state average premiums and expenditures)
- Alaska Division of Motor Vehicles — Mandatory insurance
- Alaska Division of Insurance — Consumer guide to auto insurance (rev. September 2020)
- Alaska Division of Insurance — Personal automobile rates checklist
- AIPSO — Alaska Automobile Insurance Plan
- Insurance Information Institute — Uninsured motorists (Insurance Research Council estimates)
Facts on this page were checked against these sources on October 26, 2026. NAIC averages are for 2023, the latest year the NAIC has published by state.
Have your rate shopped
Averages can't price your car and your record. Tell us the basics of your policy and Guardbrook passes them to licensed insurance agents and insurers who can quote it; you decide whether to switch.
- 1 Your cars, drivers and current policy.
- 2 How agents can reach you, and your consent.
- 3 A licensed insurance agent or insurer contacts you with quotes. Your policy stays as it is until you decide to switch.
Guardbrook is not an insurance company or agency and doesn't sell, quote or bind policies. You pay Guardbrook nothing; the licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Read next
-
Price factor
Location and ZIP code
2023 state averages ran from $808 to $1,864 per car. Why your address matters and where ZIP codes are barred.
-
Way to save
Defensive driving course discount
At least 10% in Minnesota for drivers 55+, 10% in Delaware at any age. State rules, how long it lasts, how to claim.
-
Shopping guide
When to shop for car insurance
Renewal notices (45 days ahead in Maryland), moves, new cars and drivers, and old tickets that stop counting.